Discover How Independent Contractors Turn Irregular Income Into Dependable Retirement Income — While Minimizing Their Taxes
A clear retirement and tax strategy built for independent contractors — so your strong months fund reliable income for life, a proactive plan keeps more out of the IRS’s hands, and your family stays protected if work ever stops.
Get My Retirement Paycheck SnapshotYou've Built a Strong Income — But Is Your Retirement and Protection Actually Handled?
Income That Won't Sit Still
Big months and lean months make retirement nearly impossible to plan — it's easy to under-save, over-spend, and feel behind no matter how hard you work.
No Employer Safety Net
No 401(k) match, no group life, no disability coverage handed to you — you're piecing together benefits on your own, and the gaps could wreck the family plan.
No Protection If Work Stops
If you couldn't work — or weren't here — would your family's income and future hold? Most contractors don't know, and that uncertainty quietly follows them.
A strong income doesn't protect itself — your family's future depends on a coordinated plan built for how your income actually works.
Turn 6 Hidden Tax Traps Into a Tax-Minimization Strategy
The Self-Employment Tax Bite
As a 1099 contractor you pay both halves of Social Security & Medicare — about 15.3% — on top of income tax, a cost W-2 employees never feel.
Quarterly Estimated Surprises
No employer withholds for you. A strong year can trigger a brutal April bill — plus underpayment penalties if you didn’t pay in each quarter.
The Retirement Deduction You’re Skipping
A SEP-IRA or Solo 401(k) can shelter far more than a regular IRA — often tens of thousands a year — cutting this year’s taxes while funding retirement.
The 20% QBI Deduction
The Qualified Business Income deduction can take up to 20% off your business income — but only when your income and setup are structured to qualify.
The Self-Employed Health Deduction
Your health premiums (and an HSA) can be deductible — money most contractors leave on the table every single year.
Big-Month / Lean-Month Bracket Swings
Irregular income spikes you into higher brackets in strong years; timing income, expenses, and contributions keeps more of it in your pocket.
You can’t out-earn a tax plan you never built — and for irregular income, the biggest breaks are the ones most contractors never hear about.
Trade Guesswork for a Plain-English Plan
Your Retirement Paycheck
Exactly how today's income can become a dependable monthly paycheck in retirement — in plain English.
An Irregular-Income Plan
A flexible savings rhythm that works in big months and lean months — without the stress.
Real Family Protection
Life, disability, and income protection explained simply, so your family is covered if life happens.
A Tax-Minimization Strategy
A proactive, quarter-by-quarter plan to legally minimize what you owe — SEP-IRA or Solo 401(k), the 20% QBI break, and the self-employed health deduction — so you keep more of every dollar and taxes stop competing with retirement.
Piecing It Together Alone vs. a Real Contractor Plan
Pieced Together Alone
- A random IRA and a few articles online
- "I'll get serious once income stabilizes"
- Insurance you've never really compared
- Quarterly taxes that feel like a surprise
- No plan for income if work stops
The Irregular Income Retirement & Protection System
- A clear retirement paycheck number
- A savings rule built for big and lean months
- Protection sized to your family and income
- A proactive tax-minimization strategy
- A coordinated plan that grows with you
Built for Independent Contractors in Their Peak Earning Years
Consultants & Tech Contractors
High-earning 1099 professionals running their own show without an employer plan.
Creatives & Trades Owner-Operators
Marketing, healthcare, and trades contractors with strong but uneven income.
Ages 35–50, 5–15 Years In
Mid-career, peak earning years, finally ready to plan retirement seriously.
Families Depending on You
Married or partnered, kids, a home — real people counting on your income.
Not for DIY investors who never want guidance or are looking for hype and shortcuts — this is for contractors who want clarity, numbers, and a plan they can actually follow.
The Irregular Income Retirement & Protection System
A 7-step system that turns irregular income, taxes, and missing benefits into one calm, coordinated plan.
Snapshot The Whole Picture
We run your Retirement Paycheck Snapshot and gather your income swings, accounts, debts, insurance, and family needs in one place.
Find The Benefits Gaps
We identify the missing "employer benefits" you don't have — retirement structure, life, disability, and asset protection — and prioritize them.
Build The Irregular Income Plan
A flexible monthly plan that works in big and lean months, with clear minimums, targets, and catch-up rules.
Tax Pressure Game Plan
A quarterly tax rhythm plus the write-offs and retirement deductions built for 1099 income — SEP-IRA or Solo 401(k), the 20% QBI deduction, and the self-employed health deduction — so you stop overpaying and taxes and retirement don’t compete for the same dollars.
Protection That Makes Sense
We explain life insurance options in plain English and put the right coverage in place to protect your family, income, and assets.
Wealth Engine Setup
We set up or optimize your long-term wealth plan so contributions run smoothly and match your goals and budget.
Retirement Paycheck Map
A simple retirement income strategy so you know exactly how you'll create a dependable paycheck in retirement.
From Snapshot to a Retirement Paycheck in Four Steps
Get Your Snapshot
Answer a few quick questions to get your free Retirement Paycheck Snapshot.
See Your Numbers
Your retirement paycheck estimate and your biggest protection gaps.
Book Your Strategy Review
Turn the snapshot into a calm plan built for irregular income.
Move Forward With Confidence
A clear roadmap your family is protected by — and you can actually follow.
Know If Your Retirement & Taxes Are On Track
Answer a few quick questions and get your free Retirement Paycheck Snapshot score — see where you stand on the tax, savings, and protection gaps that catch independent contractors off guard, in about 15 minutes.
- Your score across the essentials for irregular income: tax minimization, savings consistency, and protection
- Where you stand today: a strong foundation, real gaps, or action needed now
- Your biggest exposure — identify whether life, disability, or liability gaps could derail your family's plan
- Your clearest next step toward a steady retirement paycheck you can build on, big months and lean ones alike
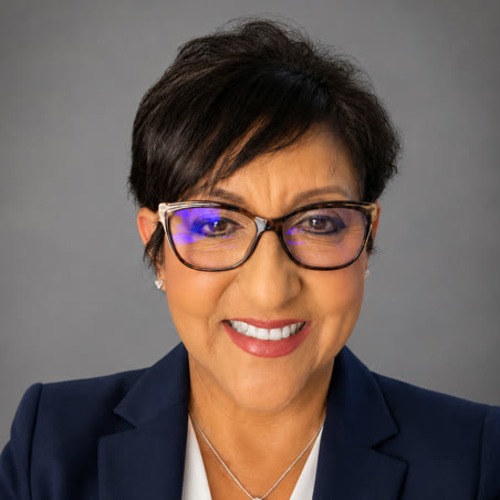
Elia Juarez
Elia Juarez is a financial strategist with Valoram Solutions who helps high-earning independent contractors across major U.S. metro and suburban markets turn irregular income into a clear retirement paycheck plan — while closing the protection gaps that can derail a family's future. She specializes in retirement income strategies, life insurance solutions explained in plain English, and long-term wealth accumulation designed for fluctuating cash flow and tax pressure. Her process starts with listening: she maps income patterns, tax realities, and family responsibilities, then builds a personalized roadmap that scales from lean months to big months without breaking. Clients consistently report relief and confidence because they finally have a plan that protects their family now, not "someday." Elia remembers the season when she quietly thought, "I need help, please," and learned that the right support and a real plan change everything. Today she's driven to give contractors the clarity, protection, and control they deserve — starting with the Retirement Paycheck Snapshot.
What Confidence Feels Like
"I thought I was the only one who felt behind because my income is irregular. Elia mapped my retirement paycheck and finally gave me a plan I can follow in big and lean months."
"No employer benefits meant I was winging protection. She explained life and disability coverage in plain English and right-sized it for my family."
"Quarterly taxes used to blindside me. Now I have a savings rhythm and a retirement plan that actually fits how my income works."
Frequently Asked Questions
I don't have an employer plan — where do I even start?+
My income is irregular — can I really plan around that?+
What exactly is the Retirement Paycheck Snapshot?+
What tax breaks do most independent contractors miss?+
Are you going to try to sell me something?+
How much does the Snapshot cost?+
Give Your Family the Certainty They Deserve
Get your free Retirement Paycheck Snapshot and build the tax-smart, protected plan your family can count on.
Get My Retirement Paycheck Snapshot